Dwelling Coverage
May help repair or rebuild the main home after a loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.
We help property owners review coverage for the house, belongings, personal liability, other structures, deductibles, roof concerns, and South Central Texas property risks. Request a quote online or call Insurance Plus for help comparing available options.
Major credit cards and EFT/ACH may be accepted depending on provider eligibility, down payment rules, billing plan, and policy type.
Payment plans, escrow handling, mortgagee billing, and automatic payment choices vary by provider.
A policy is often requested because a lender needs evidence of insurance before closing, but the coverage should be reviewed for more than the mortgage requirement. A San Antonio home may need protection for the dwelling, detached structures, personal property, liability, medical payments, and temporary living expenses after a covered loss. The limits, deductibles, roof provisions, water limitations, foundation-related concerns, and optional endorsements can matter just as much as the price.
Insurance Plus helps homeowners look beyond the basic proof requirement and think through how the property is used, how the home is built, what updates have been completed, and what local risks may affect the quote. The goal is to help match the property to the right available coverage route without confusing owner-occupied home coverage with condo, mobile or manufactured home, vacant property, or landlord coverage.
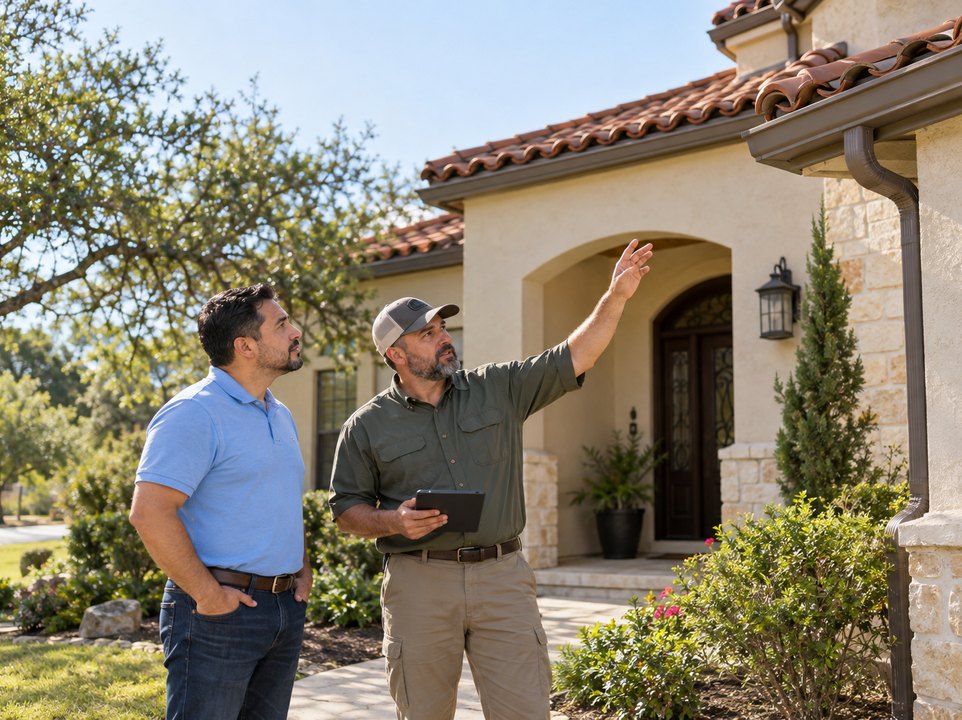
Share the property details online or call Insurance Plus. We can help review what information may be needed before a quote can be completed.
Get a QuoteLocal agency support • San Antonio property coverage options
Your policy can include several coverage parts. Availability, limits, deductibles, endorsements, roof terms, and eligibility rules vary by property and provider. We help homeowners in San Antonio Texas review the major pieces so the quote reflects the property, occupancy, roof, deductible choices, and coverage needs.
May help repair or rebuild the main home after a loss, subject to the policy limit, deductible, covered cause of loss, exclusions, and claim conditions.
May help cover furniture, clothing, electronics, appliances, and other belongings damaged or stolen after a covered event, depending on policy terms.
May help respond to certain covered liability claims involving bodily injury or property damage to others, including defense costs where covered.
May apply to detached garages, fences, sheds, and similar structures on the residence premises, subject to the policy form and selected limit.
May help with additional living expenses if a covered loss makes the home temporarily unlivable and the policy conditions are satisfied.
Wind and hail deductibles, water backup, jewelry limits, equipment breakdown, roof settlement, and other details should be reviewed before choosing coverage.
San Antonio homes can face a mix of severe thunderstorms, hail, roof wear, heat exposure, plumbing losses, theft concerns, liability exposure, and rising repair costs. Some neighborhoods include older homes with original systems or partial updates, while other areas include newer construction, hill country style properties, larger square footage, and higher replacement cost needs. Flooding is usually handled separately from a standard home policy, so San Antonio property owners should be careful not to assume every water event is covered the same way. A policy that looks acceptable at a quick glance may still have deductible, roof, water, hail, or coverage limit details that deserve a closer review.
The San Antonio housing market also includes a wide range of property styles: traditional single-family homes, townhomes, historic homes near central neighborhoods, newer Northwest Side and Far West Side construction, homes with detached garages, limestone or masonry features, larger suburban-style properties, and residences with pools or other liability considerations. That variety makes it important to provide accurate details about the property instead of assuming every home can be quoted the same way.
For an established residence, separate the original construction date from later improvements. A recently remodeled interior does not establish that wiring, supply lines or the roof were replaced. Record the work actually completed and identify additions, detached buildings and special features individually. Supply inspection findings when available instead of relying on the listing’s general description.
Consider an owner who has replaced part of a roof and repaired several interior rooms. The submission should show which roof areas remain older, whether the cause of damage was corrected, and whether another repair is planned. Keep contractor records with the relevant dates. Clear distinctions between repaired, replaced and unfinished components help prevent a quote based on the wrong condition.
A San Antonio home may sell for one amount, appraise for another, and require a different amount to repair or rebuild after a covered loss. Market value can reflect land value, neighborhood demand, school district, commute patterns, location, and buyer activity. Replacement cost focuses more on materials, labor, debris removal, local construction costs, roof type, interior finishes, and the features of the structure itself. That difference is one reason dwelling limits should not be chosen casually.
Policy limits should be reviewed with attention to the home’s construction, size, roof type, interior finishes, attached and detached structures, and any special features. The lowest quote may not be the best fit if the dwelling limit, roof terms, water limitations, or liability limit do not match the homeowner’s actual needs.
For a masonry residence, distinguish full masonry construction from brick veneer over a frame structure. Record roof material, additions, and any updates that change reconstruction assumptions.
A standard homeowners review usually begins with whether the house is owner occupied, regularly lived in, and used primarily as a residence.
Condo owners may need coverage for interior property, personal belongings, liability, loss assessment, and gaps in the association master policy.
Manufactured homes may require specialized review based on age, tie-downs, location, construction type, and provider eligibility guidelines.
A vacant home or home under renovation may not fit a normal home policy and should be reviewed before assuming coverage applies.
Homes with prior claims, aging roofs, older systems, or unusual risk details may need a more focused high-risk home coverage review.
If the property is rented to tenants, visit our landlord insurance quote page instead of using an owner-occupied home quote path.
Where vegetation or drainage is a concern, describe the specific lot and completed mitigation rather than relying on a regional label. Ask how the proposed policy handles relevant exclusions. Confirm the specific details with the provider before relying on a coverage assumption.
A useful discussion can begin with the part of the house that would be hardest to replace. Custom finishes, unusual construction or older materials deserve a realistic reconstruction estimate rather than a guess based on the loan. Our agency can help organize the questions about limits, valuation and contract restrictions before an owner compares the available proposals.
San Antonio homeowners insurance should support your specific property and owner situation. A fast quote is helpful, but a clear quote is better when the details could affect claims, billing, mortgagee proof, or long-term satisfaction with the policy.
When replacing a contract after a renewal increase, keep the current expiration date visible and compare the complete proposed terms. Check any remaining repair request or lender deadline as well. A different premium may accompany different roof settlement, deductibles or water protection. Arrange the new effective date and confirm acceptance before requesting cancellation of protection still needed.
Depending on provider eligibility, billing options may include a down payment, installment plan, mortgage escrow billing, EFT, ACH, or major credit card payment. Accepted payment methods and billing rules vary by provider, so they should be confirmed as part of the quote review rather than assumed.
A homeowner moving from renting to owning may care most about lender proof and affordability. A home near central San Antonio with mature trees, older plumbing, or an aging roof may raise different questions than a newer home on the Northwest Side, a townhome near a dense urban corridor, a hill country edge property, or a larger property with a pool. A homeowner with an older roof may need to focus on eligibility and roof settlement terms. A homeowner with recent remodeling may need to confirm whether the dwelling limit still reflects the updated structure.
The best quote conversation starts with the real situation. Is this a purchase, renewal, refinance, replacement policy, or urgent proof request? Is the house occupied now? Has the roof been replaced? Are there prior claims? Is the home titled as a condo, townhouse, manufactured home, or single-family residence? The answers can point the review in the right direction.
Homeowners often look closely at coverage only after a claim happens. It is better to review important details before a storm, fire, theft, water loss, or liability claim. Deductibles, roof settlement provisions, personal property limits, jewelry sublimit, backup of sewer or drain endorsements, and loss-of-use limits can all affect how useful a policy feels at claim time.
No policy covers every possible event. Flood, earth movement, wear and tear, vacancy, business use, intentional acts, and maintenance issues may be limited or excluded depending on the policy. Asking questions before buying can help avoid surprises and can help determine whether separate coverage or endorsements should be considered.
Ask whether wind or hail losses are included, limited, or excluded and whether a separate deductible applies. Compare actual policy wording. Ask for clarification before choosing among the available forms.
As an independent agency, Insurance Plus can help review available options instead of limiting the conversation to one company path.
Keep photographs, repair estimates, and dated invoices for major updates. Accurate records can help answer underwriting and claim questions.
We help separate homeowners, condo, mobile or manufactured home, vacant home, and landlord needs so the quote starts in the right place.
Common questions from San Antonio.
A homeowners policy may include coverage for the dwelling, other structures, personal property, liability, medical payments, and additional living expenses after a covered loss, subject to policy terms, deductibles, limits, and exclusions.
Roof age, roof material, visible condition, prior hail damage, and repair history may affect eligibility, pricing, deductible options, and available roof claim settlement terms.
Yes. Condo and manufactured home insurance may require separate review because coverage forms, property responsibilities, building details, and underwriting guidelines can differ from a standard owner-occupied house.
Rates can vary based on location, home age, roof age, construction type, square footage, loss history, coverage limits, deductible choices, selected endorsements, and provider eligibility rules.
No. A home you occupy and a property rented to others often need different coverage. Rental homes and investment properties may require landlord insurance rather than a standard home policy.
Tell Insurance Plus about the property, desired effective date, lender needs, roof details, and coverage preferences. We can help review the available quote path.