Modular Home Coverage
May help repair or replace the modular home after a covered loss, subject to policy terms and selected limits.
Insurance Plus helps Texas owners of modular or industrialized homes review homeowners insurance options for the dwelling, belongings, liability, weather risks, deductibles, and payment preferences.
Serving Texas since 1997 • Licensed Texas independent agency
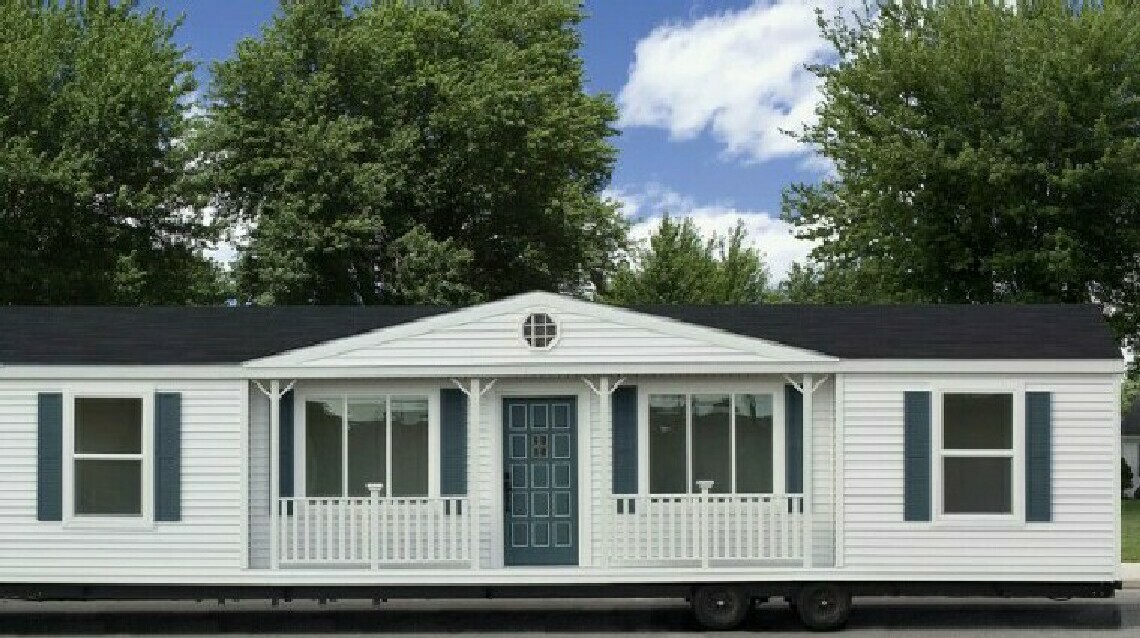
In Texas, an industrialized or modular home is built in one or more factory-produced modules and installed as a permanent residential structure. It is not a HUD-code manufactured home. Texas modular housing is constructed to the same applicable building codes as site-built housing and must be installed on a permanent foundation system.
That distinction matters when shopping for insurance. A home can be factory-built without being a manufactured home, and a modular home may be reviewed more like conventional site-built housing depending on the property and insurer. Insurance Plus helps owners identify the construction type and review appropriate homeowners coverage options.
Share your property details online or call Insurance Plus if you want help reviewing what may be needed before your quote can be completed.
Request Home QuoteLocal agency support • Texas modular home coverage options
Major credit cards and EFT/ACH may be accepted, depending on provider eligibility and payment plan.
Availability, billing plans, and down payments vary by provider.
Coverage availability, limits, deductibles, endorsements, exclusions, and eligibility vary by provider and property details.
May help repair or replace the modular home after a covered loss, subject to policy terms and selected limits.
May help cover furniture, clothing, electronics, appliances, and other belongings damaged by a covered cause of loss.
May help protect against certain covered claims involving injury or property damage to others.
Garages, sheds, decks, porches, and other structures may need review depending on policy terms and property details.
May help with additional living expenses if a covered loss makes the home temporarily unlivable.
Deductibles, down payments, billing plans, roof provisions, and payment options should be reviewed before choosing coverage.
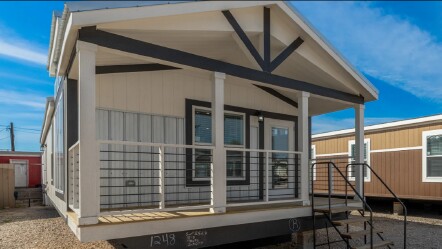
Modular homes are a separate construction category from HUD-code manufactured homes. Texas industrialized housing is built to codes applicable to site-built housing, installed on a permanent foundation, and generally becomes part of the real property. A provider may review the home’s construction documentation, foundation, roof condition, location, occupancy, replacement cost, and prior claims.
Texas weather can also affect coverage review. Wind, hail, severe storms, fire, water concerns, roof age, and deductible choices should be reviewed carefully before selecting a policy.
A modular-home quote may depend on the home’s location, construction details, permanent foundation, replacement cost, roof condition, prior claims, occupancy, selected limits, deductible choices, and attached or detached structures. If available, information showing that the home was constructed as Texas industrialized housing can help distinguish it from a HUD-code manufactured home.
Accurate property information helps prevent delays. Before requesting a quote, it can help to know whether the home is owner-occupied, rented to someone else, located on private land, used seasonally, or financed by a mortgage lender.
Modular homes should not automatically be classified as mobile or manufactured homes simply because they were factory-built. In Texas, modular or industrialized homes are built under a different code system and installed on permanent foundations. The appropriate insurance route can depend on construction documentation, occupancy, lender requirements, replacement cost, and provider guidelines.
If your home instead carries HUD manufactured-home certification labels or was built to the federal HUD Code, review our Texas manufactured home insurance page. For traditional mobile-home terminology and older units, visit our Texas mobile home insurance resources.
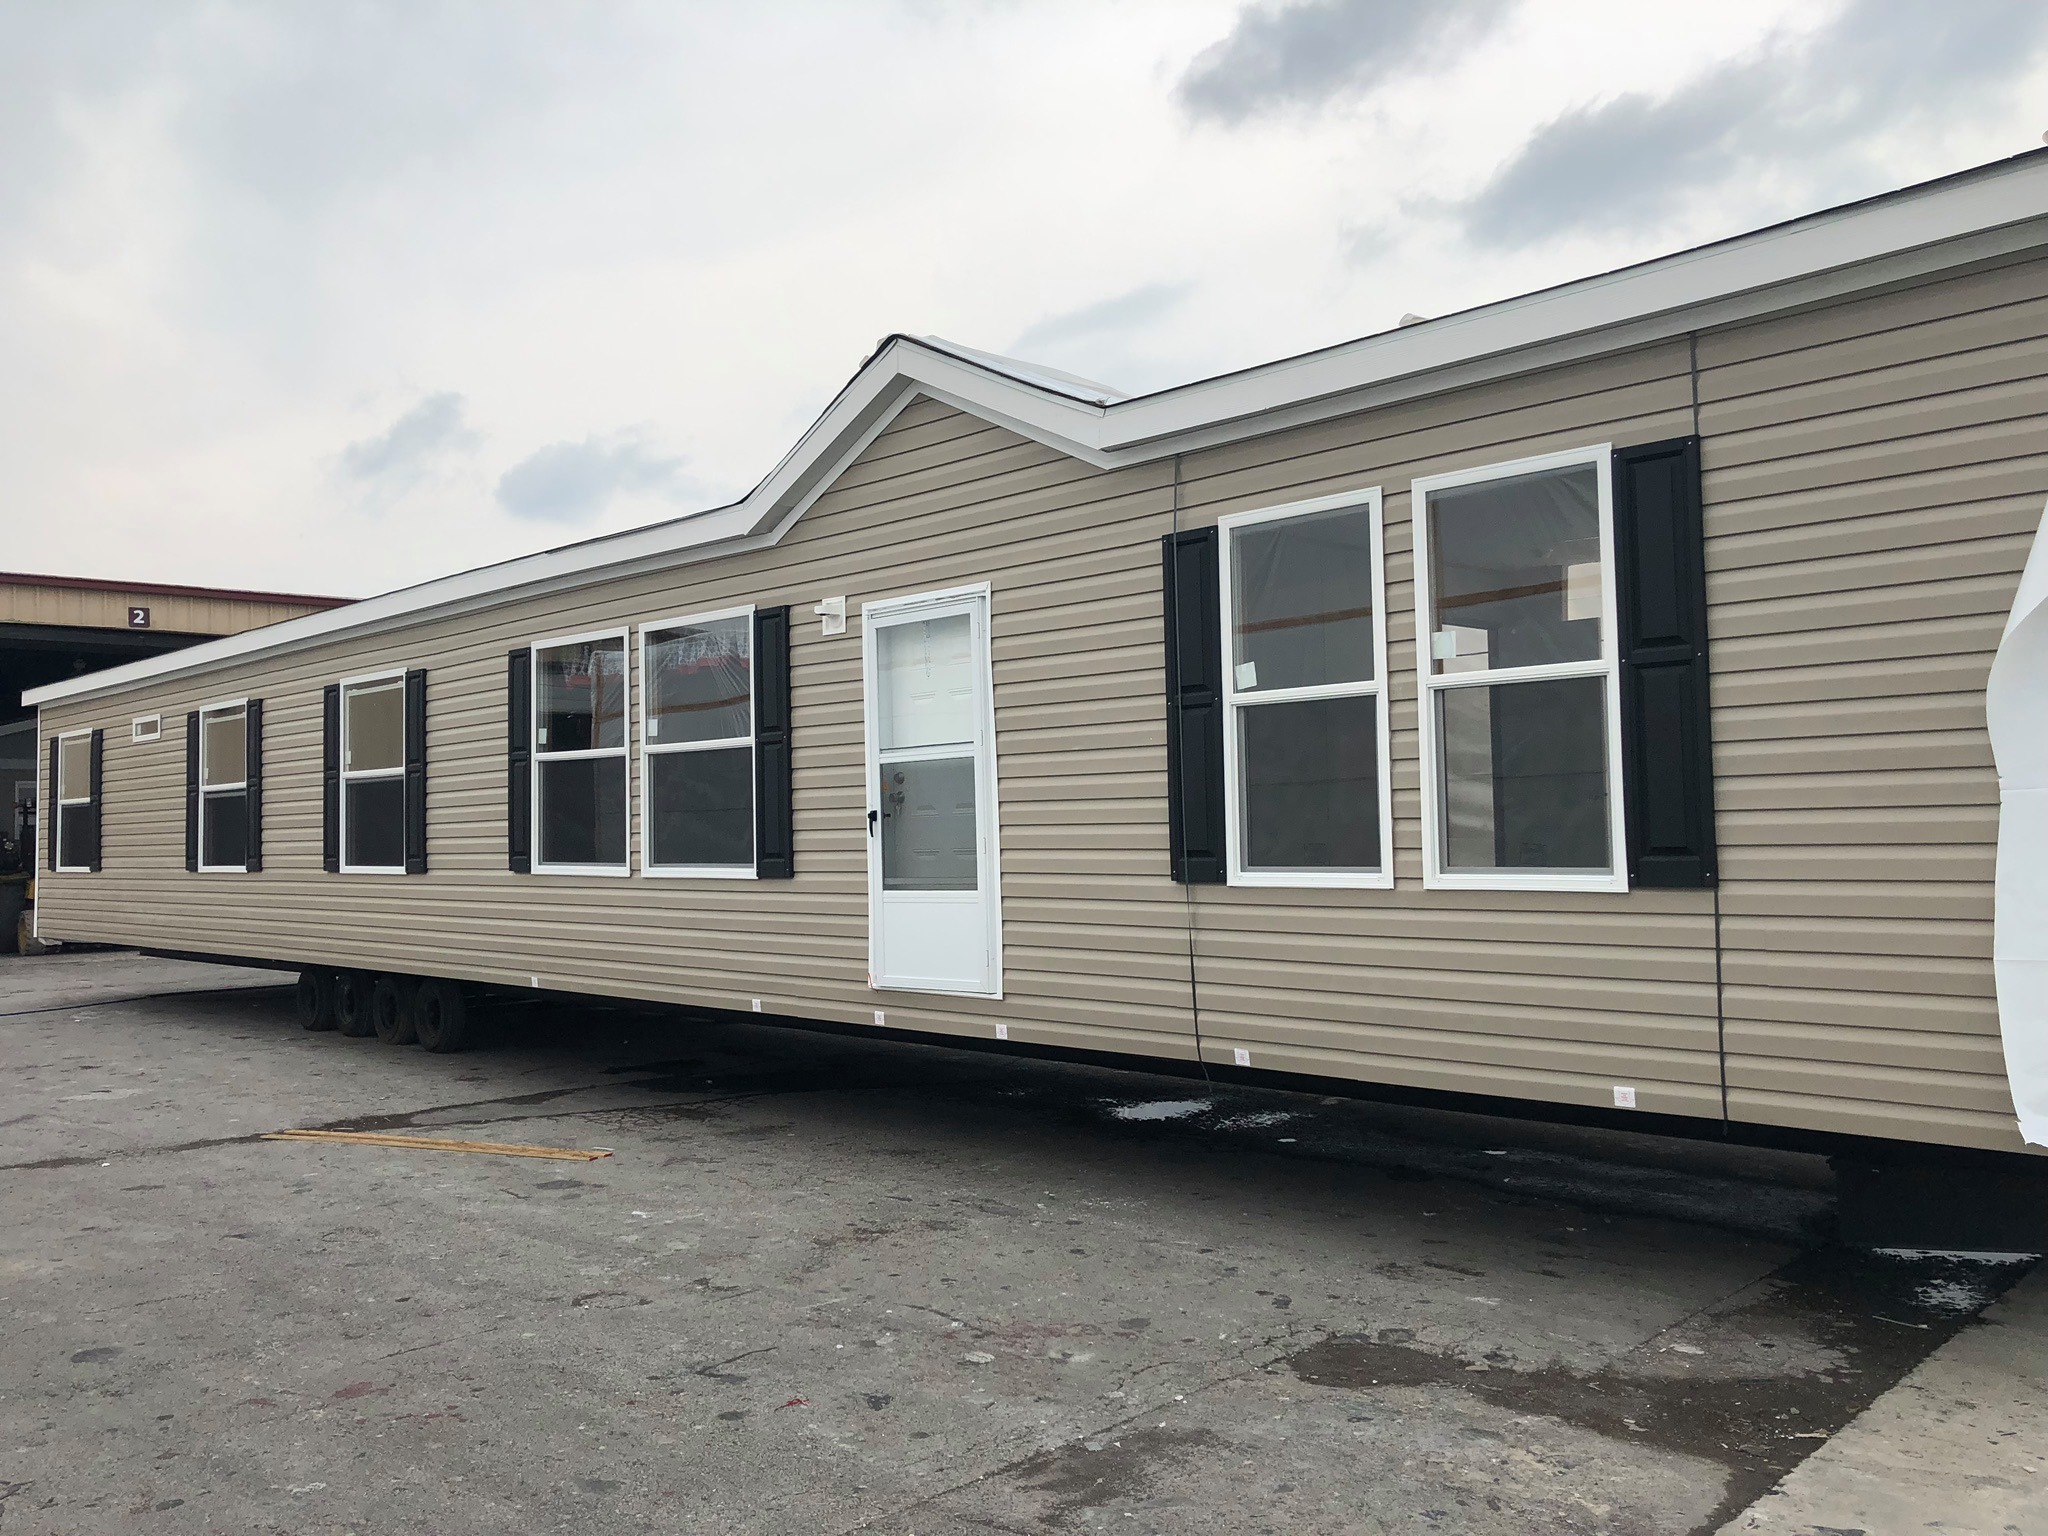
Modular home coverage is easier to review before a claim than after one. It is important to understand the home coverage limit, personal property protection, liability coverage, deductibles, attached structures, and payment options before a loss happens.
Insurance Plus can help explain what information may be useful for a quote and whether another coverage type may be more appropriate. If the property is rented to tenants, review landlord coverage. You can also return to the Insurance Plus homepage to review personal, property, and business insurance options.
Common questions about modular home insurance in Texas.
Yes, they are different construction categories. In Texas, modular or industrialized homes are built to codes applicable to site-built housing and installed on permanent foundations. Manufactured homes are built to the federal HUD Code. Insurance treatment still depends on the individual property and provider guidelines.
Coverage may include the modular home, personal belongings, liability protection, additional living expenses, and certain attached or detached structures after a covered loss.
A quote may be affected by the home's location, construction details, foundation, roof condition, occupancy, prior claims, coverage limits, deductibles, and payment options.
A modular home rented to tenants may require landlord or rental property coverage instead of owner-occupied home coverage.
Yes. You can request a quote online or call Insurance Plus for help reviewing modular home coverage information and quote requirements.
Request a quote and review available options for modular homes, belongings, liability, deductible choices, weather risks, roof details, and payment preferences.