Independent agency · Serving Texas since 1997214-351-4097
Insurance Plus
Southeast Texas rental-property owners

Beaumont Landlord Rental Property Insurance

Compare Beaumont landlord insurance quotes with the building, rental use and storm exposure in view. Review available limits and deductibles before choosing coverage. Insurance Plus serves owners throughout Texas; select the quote option for your building size.

An owner and property manager reviewing Beaumont landlord insurance outside a shaded rental home

Payment & billing options

Methods and installment plans vary by carrier. A quote request does not take payment or bind coverage.

Begin with the coverage questions that matter here

Separate wind, flood and building protection

A single premium does not tell the whole story. Before comparing proposals for a Southeast Texas rental, identify which policy covers each exposure and what you would pay after a loss.

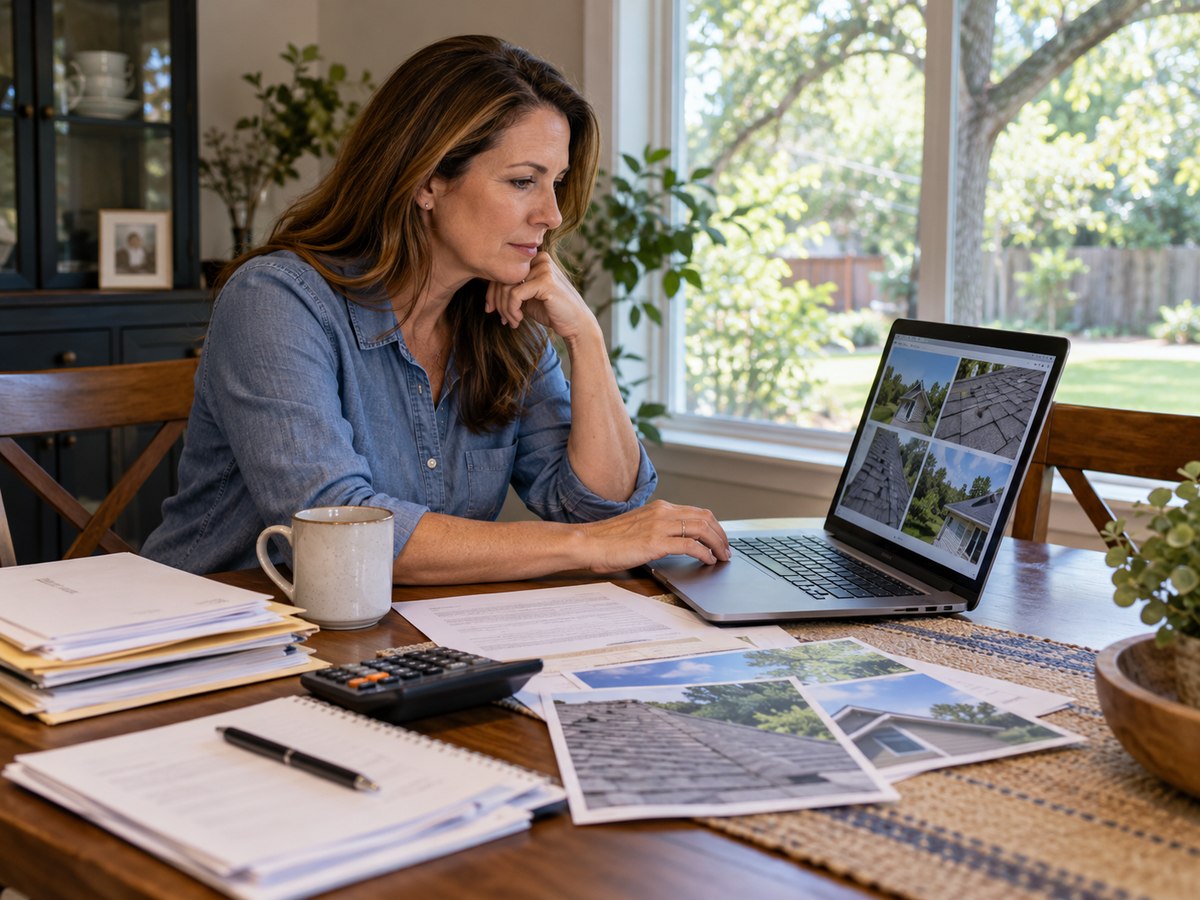
A property owner reviewing roof repair photographs, invoices and a calculator at her table

Roof records and windstorm terms

Ask whether wind and hail are included or excluded, and whether a separate wind policy is needed. Review any wind, hail or named-storm deductible and the basis used to calculate it.

Compare roof settlement with the building’s settlement terms. Replacement cost and actual cash value can produce different outcomes, and roof-specific restrictions may apply even when the dwelling has broader protection.

After prior storm damage, distinguish permanent repairs from temporary work. Keep roof dates, photographs and invoices together; a closed claim does not establish that every repair is complete. If an inspection is required, ask about its timing and any repairs needed before the proposal can be accepted.

Review windstorm coverage options →
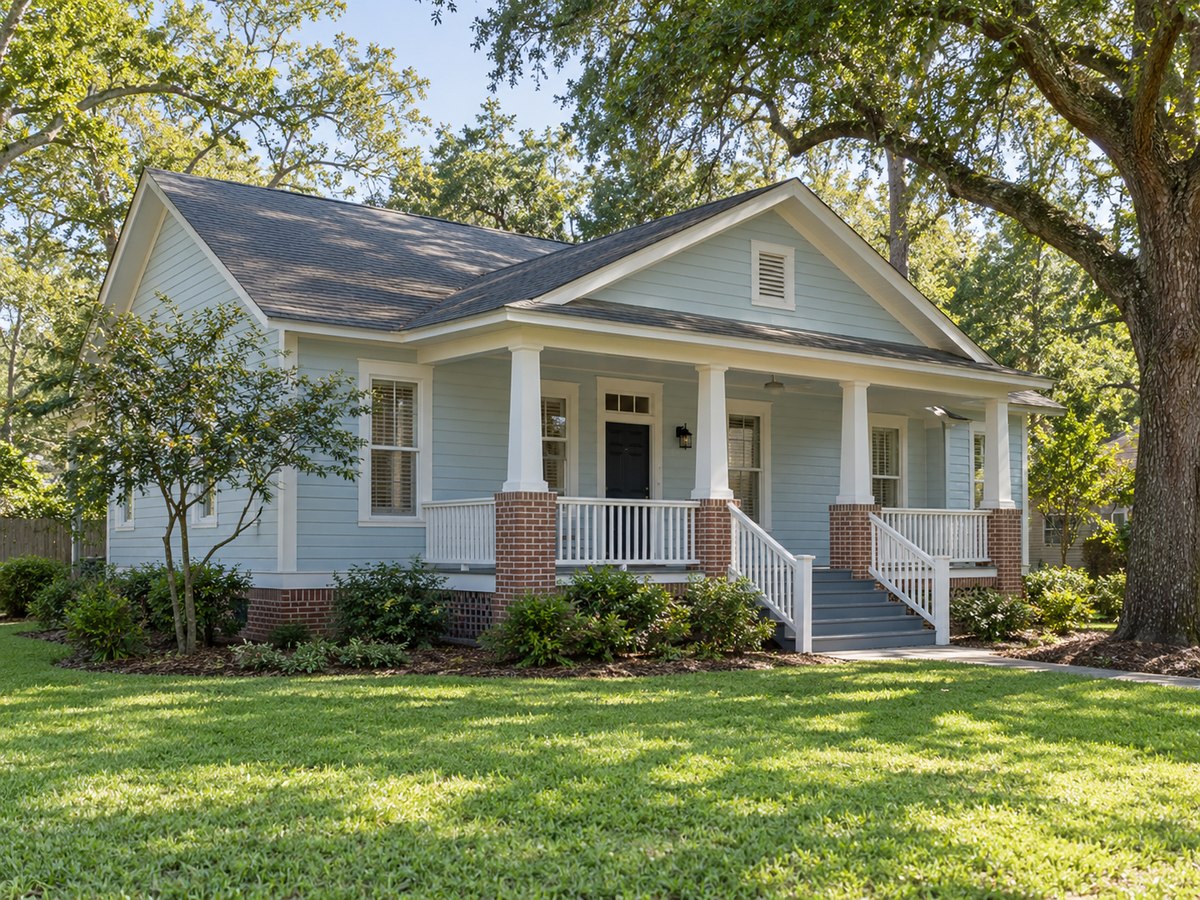
A detached rental home representing Beaumont rental property insurance coverage needs

Flood and the individual address

Standard dwelling policies generally exclude flood. Investigate separate protection rather than assuming a building policy will pay for rising water, even when wind coverage is included.

Review the property’s loss history, elevation and drainage information alongside lender requirements. The City’s floodplain maps and information can help you investigate an address; a neighborhood name alone does not establish the risk.

Compare flood limits, deductibles and any waiting period separately. If windstorm eligibility requires certification, ask which building and improvement records apply before relying on a proposed placement. Also distinguish flood from plumbing leaks or water backup; each needs its own review of exclusions and available protection.

Explore separate flood protection →
Describe the rental as it stands today

Beaumont rental property insurance for different ownership situations

For Beaumont rental property insurance, the application should reflect actual condition, ownership and occupancy—not the finished renovation or future tenant you expect.

A former home or inherited house

Tell the agency when an owner-occupied home becomes a rental. Supply inspection findings, roof age and documented system updates. Identify detached structures or a separately occupied garage apartment. Explain who now owns the property, including an estate or business entity, and provide the correct mortgage information.

Student or workforce occupancy

For a Lamar-area rental or a furnished property, explain the lease arrangement. Separate room leases, unrelated occupants and short stays can require a different review from a house leased to one household. List furnishings you supply and explain whether management, cleaning or access arrangements change between occupants.

An established neighborhood property

Old Town, South Park and West End addresses can have different construction and renovation histories. Individual roof, electrical, plumbing and foundation information matters more than a generic citywide assumption. Identify unrepaired issues separately from completed updates, and keep the relevant inspection findings with your building records.

Building limits should reflect a reconstruction estimate rather than simply the purchase price or loan balance. Include owner-owned appliances and furnishings where needed. A building owner’s policy generally does not protect a tenant’s belongings; tenants should review their own coverage.

When the property or account changes

Keep coverage aligned through repairs and growth

Occupancy changes and additional locations deserve a fresh review before a renewal or new placement.

A property owner inspecting a freshly painted empty living room between tenants

An empty rental awaiting repairs

Disclose disconnected utilities, open walls, worker access and any unresolved damage. An empty building awaiting electrical repairs is different from an occupied home needing minor maintenance.

Review Beaumont rental property insurance before extended vacancy, major renovation or a change to short-term use. Give the expected completion date and update the agency when work is finished or tenants return.

Keep dated photos and invoices so the review follows the property’s actual condition.

Read the vacant rental-property guide →
A small brick and siding apartment building with a landscaped walkway

Several rentals or a larger building

List building limits, roof terms, deductibles and income protection for each address. Include separate wind or flood policies so a combined premium does not hide a gap at one location.

Identify ownership entities, mortgages, managers and loss histories. Properties can be reviewed together without assuming they will all qualify for the same policy or carrier.

For five or more units, prepare a building schedule, unit count, occupancy and rental-income details for our apartment form. Describe common walkways and the property manager’s maintenance responsibilities.

Request a multifamily quote →
Prepare the application, then compare the terms

Landlord insurance for Beaumont rentals: review your options

Have the address, unit count, year built, square footage and construction type ready. Include roof age, major updates, current occupancy and the coverage date you need.

Share prior wind, water, fire and liability losses, current declarations and repair records. Describe cancellations, nonrenewals or gaps accurately rather than guessing at dates or omitting unfinished damage.

Insurance Plus can help you review Beaumont landlord insurance for an eligible residential rental. Insurance Plus has served Texas since 1997; our independent agency can explain available proposals and the underwriting details they require.

  • Compare equivalent building and liability limits.
  • Check roof valuation, exclusions and deductibles.
  • Review eligible loss-of-rents limits and repair periods.
  • Confirm inspection and binding requirements.
Request a Residential Quote
An adviser and property owner reviewing a paper application together
Organized ownership, building and repair records make quote questions easier to resolve.

Read the policy behind the price

DP1, DP2 and DP3 labels help organize a comparison, but the actual form and endorsements control. Review basic named-peril, broader named-peril and special dwelling options alongside exclusions and settlement terms. Loss-of-rents coverage generally concerns eligible income interruption after covered damage, rather than ordinary nonpayment or routine vacancy.

A form submission requests a review; it does not issue a policy. Confirm approval, effective dates, binding instructions and any required payment before relying on coverage.

Nearby cities and communities

We also help rental-property owners in these nearby Southeast Texas communities.

VidorService area
NederlandService area
Port NechesService area
LumbertonService area
GrovesService area
Port ArthurService area
ChinaService area
Sour LakeService area

Questions before arranging coverage

Is wind coverage automatically included?

Do not assume it is. Check the proposal for wind and hail exclusions, separate deductibles and any separate policy requirements. Eligibility and terms depend on the property and the available market.

Does a dwelling policy cover rising floodwater?

Standard dwelling policies generally exclude flood damage. Review separate flood protection for the address, including lender requirements, limits, deductibles and any applicable waiting period.

What if storm repairs are not finished?

Disclose the remaining damage and temporary repairs before requesting coverage. Provide available photographs, invoices and completion estimates. The insurer may require repairs, an inspection or a different coverage arrangement.

Are student rentals or furnished units treated differently?

Occupancy and rental arrangements can affect eligibility. Explain room-by-room leases, furnishings, short-term stays and any owner occupancy so the submission describes the actual use.

Will income protection replace unpaid rent?

Loss-of-rents coverage generally concerns eligible income loss following covered property damage. Ordinary nonpayment, eviction and an unrented unit are different situations. Review the policy’s triggers and limits.

Which form should I use, and when does coverage begin?

Use the residential form for one to four units and the apartment form for five or more. Submitting either form requests a review; coverage begins only when approval, binding instructions and the effective date are confirmed.

Does owner liability replace a tenant’s policy?

No. Owner liability and tenant coverage address different insured interests. Review protection for the premises and your responsibilities separately from the tenant’s belongings and personal liability. Neither replaces routine maintenance or accurate disclosure of the property’s features.

Can coverage be reviewed before a rental purchase closes?

Yes. Share the closing date, ownership information, lender requirements and available inspection records early. Review the proposed limits and deductible before authorizing placement. A quote request does not guarantee approval or make coverage effective for the closing.

Ready to review the building you rent out?

Choose the appropriate property form. Insurance Plus serves owners throughout Texas: 214-351-4097.

Quote · 1–4 unitsQuote · 5+ units